UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock
The UK introduced Vaping Products Duty on 1 October 2026. HMRC guidance explains how physical stamps, digital codes and the stock transition fit together.
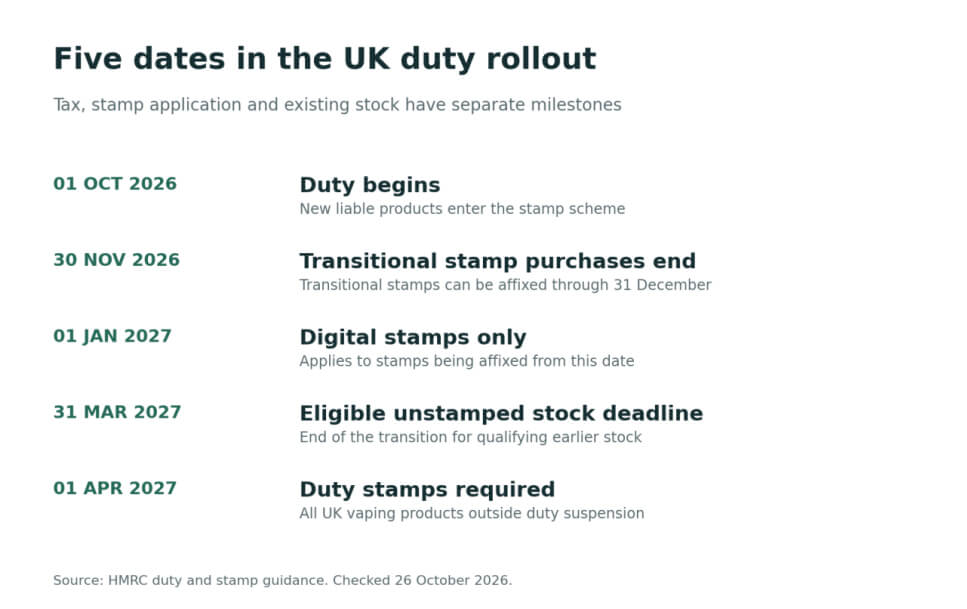
The UK’s Vaping Products Duty and Vaping Duty Stamps Scheme took effect on 1 October 2026. HM Revenue & Customs subsequently updated its wholesale and retail guidance on 7 October, clarifying the treatment of existing unstamped stock. The implementation has several stages, rather than one deadline applying to every product. [1][3]
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock
What changed on 1 October
The new excise duty is £2.20 per 10ml of vaping liquid manufactured in, or imported into, the UK from 1 October. It applies whether or not the liquid contains nicotine. Payment is accounted for at the relevant duty point; authorised duty-suspension arrangements can defer that point. [1]
HMRC identifies approved manufacturers, importers and warehousekeepers as the parties paying the duty. The stated rate is not a government-set retail price increase: whether businesses pass that cost onward is a commercial decision. VAT continues to apply separately. [1]
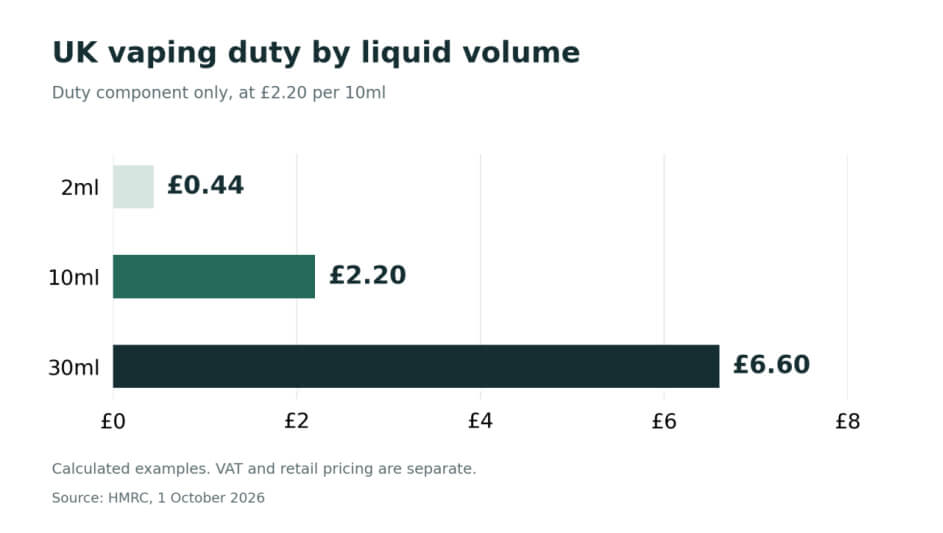
At this rate, the duty component is £0.44 for 2ml, £2.20 for 10ml and £6.60 for 30ml. These are calculations for the liquid volume alone, before considering VAT or a business’s pricing decisions. [1]
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock (2)
A digital stamp is still a physical label
HMRC’s stamp guidance describes a physical security label attached to the outermost retail packaging. Opening the pack must damage either the packaging or the stamp. A digital stamp adds a scannable code that supports authentication and supply-chain tracing; it does not replace the physical label. [2]
During the initial rollout, transitional stamps have physical security features without a digital element. They are not scanned. Transitional stamps remain available to purchase until 30 November 2026, while digital stamps are also available. From 1 January 2027, only digital stamps may be affixed. That is a rule about applying new stamps, which should be distinguished from the separate deadline for existing unstamped stock. [2]
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock (3)
The stock transition ends in April
HMRC’s guidance permits qualifying unstamped products produced or imported before 1 October 2026 to remain in the transition until 31 March 2027. The relevant distinction is when stock was produced or imported, rather than simply when a retailer received it. Records must support the reason a product remains unstamped. [3]
From 1 April 2027, all vaping products outside duty suspension in the UK must carry a duty stamp. The January deadline for digital stamp application therefore does not extend the March end date for eligible unstamped stock, or postpone the duty that began in October. [2][3]
UK Vaping Duty Begins with Separate Deadlines for Stamps and Existing Stock (4)
Why the distinction matters
During the transition, packaging may legitimately look different across otherwise similar products. Eligibility cannot be established from appearance alone: HMRC’s guidance places emphasis on origin, production or import dates, and the supporting commercial records. It says relevant records should be retained for at least six years. [3]
For readers following the rollout, three questions help interpret a report accurately: when did the duty begin, which type of stamp is being discussed, and does the report concern newly produced goods or qualifying earlier stock? Keeping those questions separate avoids treating a phased implementation as a single packaging change.
Sources
[1] HM Revenue & Customs. New Vaping Products Duty comes into effect — 2026-10-01
[2] HM Revenue & Customs. How vaping duty stamps work — 2026-04-01; updated 2026-08-26
[3] HM Revenue & Customs. Handling wholesale or retail vaping products in the UK — 2026-07-09; updated 2026-10-07